


Owners Club is FanClub Sports Capital’s newsletter and investment community. We breakdown the recent topics and news in sports investment and M&A
Access a list of active opportunities on our platform here. Please reply to the email for password protection.
Overview
The New York Knicks enter the 2026 NBA Finals on Wednesday against the San Antonio Spurs — their first trip to the championship round since 1999 — having won 11 consecutive playoff games by an average margin of 23.8 points, the greatest 11-game stretch in the 80-year history of the NBA. Jalen Brunson has positioned himself on the short list of all-time great Knicks, and Karl-Anthony Towns has provided the frontcourt anchor that prior Knicks iterations lacked. It is, by any measure, the most commercially valuable moment Madison Square Garden Sports has experienced in decades. The irony is that the franchise is heading into the Finals as a publicly traded company — and its shareholders are still, structurally, underweight on the value they actually own.
Madison Square Garden Sports Corp. filed its Form 10 Registration Statement with the SEC in May 2026 — a formal step toward separating the New York Knicks and New York Rangers into two independently traded public companies. The proposed spin-off, which would require approval from both the NBA and NHL, is structured as a tax-free distribution. Its stated rationale is straightforward: “enhanced strategic flexibility, its own defined business focus, and clear characteristics for investors.” But the deeper logic is about a structural discount that has suppressed the Dolan family’s balance sheet for years — and about how that same discount, when applied to other publicly held sports assets, consistently invites a particular type of institutional investor to step in.
Here are several developments driving the formation of private capital in pro sports:
Email or book a call with our CEO David Mirynech to find out more about how to invest in pro sports private equity globally
1. The Math Behind the MSG Split
The Valuation Gap: The arithmetic is unusually clean. Sportico’s most recent valuations place the Knicks at $9.85 billion and the Rangers at $3.65 billion — a combined private-market value of $13.5 billion. MSG Sports’ current enterprise value in public markets is approximately $9.6 billion. That is a 29% discount to the sum of its parts.
This is not a minor rounding error. It represents roughly $3.9 billion in latent value that public markets have, for structural reasons, declined to assign to MSGS shares.
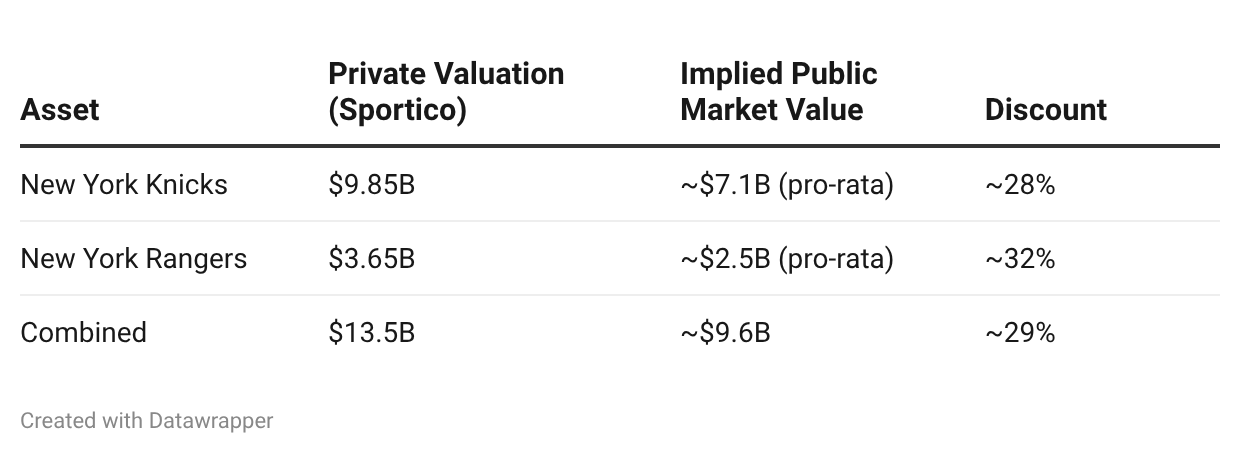
Guggenheim analysts noted that MSGS shares would need to trade at an 84–94% premium to be in line with third-party franchise estimates — a figure that illustrates not merely mispricing but a fundamental mismatch between how public equity markets and private sports capital value the same underlying assets.
The Dolan Factor: The discount has a name. Wall Street has long applied what it calls the “Dolan discount” — a structural haircut on MSGS shares that reflects the complexity of the Dolan family’s broader corporate ecosystem. James Dolan controls MSG Sports, MSG Entertainment (venues including Madison Square Garden, Radio City Music Hall), and Sphere Entertainment — four publicly traded entities with overlapping governance, related-party transactions, and cross-subsidization flows that outside investors find difficult to model accurately. The family holds only 21% of MSGS shares economically but maintains voting control through super-voting share structures. The result is a multi-asset corporate web in which the sports assets are effectively trapped. Activist shareholder Boyar Value Group captured it bluntly in a June 2025 open letter: “The persistent gap between private market values and public market pricing is no longer just a missed opportunity — it’s a failure to act in the best interest of shareholders.”
The Analyst Take: The spin-off is, at its core, an attempt to convert conglomerate structure into pure-play structure. By trading as independent entities, each team’s cash flows, media rights exposure, and growth trajectory become legible to a different class of investor. Seaport Research Partners analyst David Joyce noted that the separation “makes minority stake sales easier, as there are two distinct teams’ business models, which makes for a clearer investment vehicle.” The implication is not merely value unlocking — it is an invitation to institutional capital.
2. The Multi-Club Model: Why Consolidation Has Been the Dominant Trend
The Consolidation: The MSGS split runs counter to the dominant structural trend in North American sports ownership over the past decade. Across every major league, the most durable ownership structures have been multi-franchise platforms — conglomerates that operate several professional teams under shared infrastructure, shared services, and centralized commercial strategy. The operational logic is straightforward: the fixed cost base (front office, legal, analytics, sponsorship sales, data infrastructure, real estate) can be spread across multiple revenue-generating franchises, improving margin and reducing administrative duplication.
The most mature examples in North America tell the story clearly:
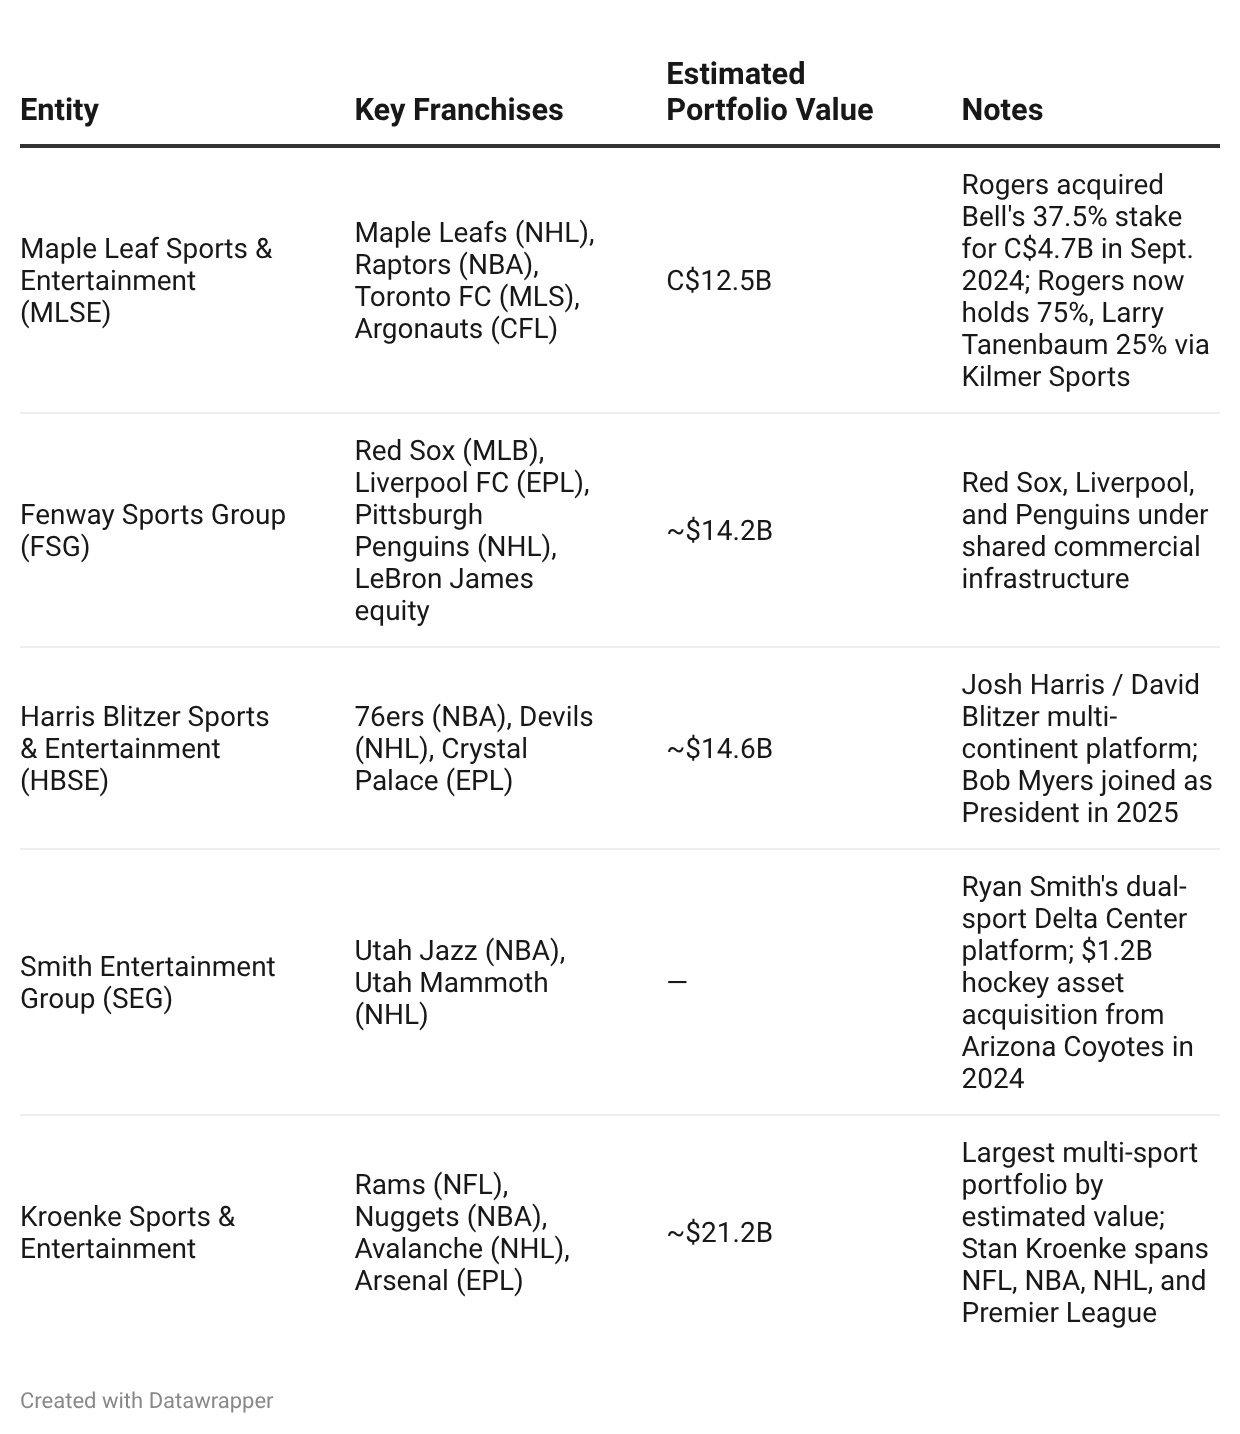
The Operational Thesis: What these platforms have in common is an ability to run unified commercial operations — shared sponsorship sales, unified data and analytics, centralized media production, real estate leverage through arena ownership — across multiple franchises. MLSE’s Toronto model is perhaps the clearest demonstration: the Maple Leafs, Raptors, and Argonauts all play in MLSE-owned or operated venues, share a sponsorship infrastructure, and contribute to a media rights package that made Rogers willing to pay C$4.7 billion for Bell’s 37.5% stake — implying the full entity at C$12.5 billion and making MLSE one of the most valuable sports conglomerates in the world.
Smith Entertainment Group illustrates the model at an earlier stage: Ryan Smith’s acquisition of the Utah Jazz in 2020 gave him control of the Delta Center. When the NHL granted SEG an expansion franchise in 2024 and Smith acquired the Arizona Coyotes’ hockey assets for $1.2 billion, the rationale was immediate: two major professional leagues sharing a single arena, a single front office infrastructure, and a single urban market footprint — compressing the cost of the second franchise while amplifying the commercial value of the first.
The Analyst Take: The MSGS split is not necessarily a repudiation of the multi-club model — it is more precisely an attempt to escape a specific malfunction of it. MSG’s problem was not consolidation per se; it was a corporate structure so opaque, and a governance dynamic so Dolan-specific, that the bundling of the two assets created a persistent negative premium rather than a positive one. The distinction matters: MLSE, FSG, and HBSE generate multi-club operating advantages. MSG Sports generated multi-club complexity penalties.
3. The Public-Private Valuation Gap: A Structural Feature, Not a Bug
The Discount: The MSG Sports situation is not an anomaly. Public sports equities have historically, and consistently, traded at a discount to what the same assets would command in private transactions. The discount reflects several structurally embedded realities: public companies are subject to compensation disclosure, executive pay tax provisions, transparency obligations, and quarterly earnings pressure that private ownership avoids entirely. They also cannot benefit from the scarcity-value premium that drives private sports transactions — there are only 124 teams across the four major North American leagues, and approximately 8,000 securities trading on U.S. exchanges. The scarcity bid that a private buyer can apply does not translate into public equity pricing.
The precedents are consistent:
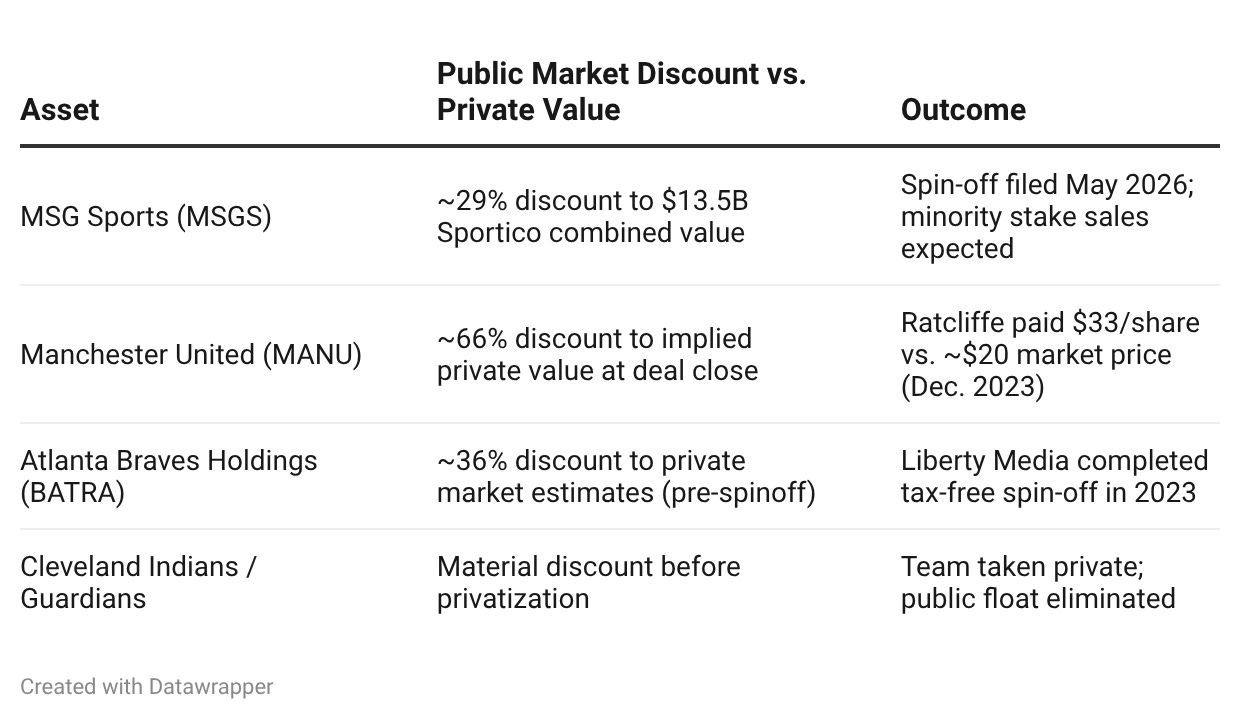
The Ratcliffe Template: The Manchester United case deserves particular attention because it establishes a repeatable playbook. United listed on the New York Stock Exchange under Glazer family control, where it consistently traded at a steep discount to what private-market investors assessed as its intrinsic value. The public float attracted activist pressure, disclosed internal financials, and created a transparent entry point for a financially sophisticated buyer who could observe the gap and price it. When the Glazers hired Raine Group in late 2022 to explore strategic options, Jim Ratcliffe’s INEOS entered a process that resulted in a December 2023 agreement: $33 per share for a 25% stake, implying a total club valuation of approximately $6.3 billion inclusive of debt — at a time when the publicly traded share price was approximately $20. Ratcliffe paid a 66% premium to the public market price. The public market, in effect, had been advertising a discounted asset for years. INEOS read the signal and acted on it.
The structural parallel to MSGS is direct. As Silver Lake — which currently holds a 10% stake in MSG Sports — and other potential minority investors evaluate the post-spin Knicks and Rangers as separate investment vehicles, the same dynamic applies: a clearly priced public market, an observable discount to private-transaction precedent, and an opportunity for a sophisticated institutional buyer to step in at a level that represents genuine value relative to what a control buyer would pay for the same asset.
The Analyst Take: The new federal tax provisions — which expand compensation deduction limits to cover the top ten highest-compensated employees starting in 2027 — add a specific and quantifiable headwind to the public ownership model. An independent Knicks entity would face an estimated $55.4 million incremental tax liability on $195 million in executive and player compensation; the Rangers entity would absorb approximately $19.8 million in additional tax on $76 million in payroll. These are real costs that private owners do not bear in the same way. They accelerate the economics of privatization and minority investment simultaneously.
4. The Structural Invitation: How Discount Becomes Deal
The Mechanism: What the public-private discount ultimately does is convert a governance problem into a capital markets opportunity. When a publicly traded sports asset consistently trades below its demonstrable private value — whether due to conglomerate complexity, management control structures, or the fundamental mismatch between scarcity-value pricing and public equity mechanics — it functions as an open invitation to private capital. The bid-ask spread between the public market price and the private transaction value is, effectively, the entry premium available to an institutional buyer who can tolerate the timeline and structure the entry correctly.
The MSGS spin-off, once complete, will do several things simultaneously:
Simplify the investment thesis for each team to a pure-play equity with defined cash flows, a specific media rights profile, and a clear competitive position in its league
Reduce the conglomerate discount by eliminating the cross-subsidization and governance opacity created by the Dolan corporate web
Enable targeted minority investment — a Knicks-specific or Rangers-specific institutional entry, rather than an undifferentiated claim on a mixed-asset holding company
Set a market reference price — a publicly observable valuation against which private investors can benchmark their internal assessments and identify whether the gap justifies a premium offer
This is structurally similar to what happened when Liberty Media separated Atlanta Braves Holdings into its own publicly traded entity in 2023. The spin-off narrowed the discount, clarified the investment thesis, and made the Braves a legible target for the kind of private buyer — typically a billionaire principal or a multi-club operator seeking to add a franchise — who had previously been deterred by the complexity of dealing with Liberty’s layered corporate structure.
The Consolidation Reversal: There is an irony embedded in this moment. The dominant multi-club playbook — MLSE, FSG, HBSE, Kroenke — has been to aggregate sports franchises inside unified operating entities precisely because the shared infrastructure model generates real economic value. Yet the MSGS experience demonstrates that aggregation without operational coherence, or aggregation behind a governance structure that markets cannot parse, produces the opposite result. The lesson is not that consolidation fails — it is that the market values operational integration and penalizes corporate complexity. MLSE works because Rogers and Tanenbaum have built a genuinely integrated sports and media platform. MSG Sports did not work because it was four publicly traded entities intertwined through related-party transactions that obscured rather than clarified value.
The Analyst Take: For private equity sponsors and multi-club operators evaluating the post-spin Knicks and Rangers, the opportunity structure is well-defined. A minority stake in an independently traded Knicks entity — at a price that still reflects a meaningful discount to private-transaction precedent — offers a combination of current-yield exposure (arena economics, NBA media rights, playoff revenue) and long-term capital appreciation in one of the scarcest, most globally recognizable franchise assets in professional sports. The Rangers, as the NHL’s second-most valuable franchise by Sportico’s estimates at $3.65 billion, offers comparable dynamics in a league whose media rights trajectory, following ESPN/Turner deals and NHL Network expansion, is firmly upward. Neither team will be cheap. But both, separated and cleanly structured, will be more investable than either has been inside the current conglomerate.
5. What the MSGS Experience Signals for Future Sports IPOs
The Deterrent Effect: The Dolan discount is not a cautionary tale unique to one family’s governance choices. It is a data point that every prospective sports franchise IPO candidate must now internalize. Fenway Sports Group, Maple Leaf Sports & Entertainment, Harris Blitzer Sports & Entertainment, and Smith Entertainment Group all represent multi-sport conglomerates that have, at various points, attracted speculation about a potential public listing. The MSGS experience — a persistent 29% discount to private value, activist shareholder pressure, a complex demerger process requiring dual league approvals, and incremental tax liabilities that private owners do not face — provides a specific and quantifiable argument against that path.
The core problem is structural. Public markets price sports assets on cash flow and earnings — and most major franchises, by those metrics, are not compelling businesses. The Knicks and Rangers combined lost $22 million after taxes and interest in the 2024–25 fiscal year. That is not an anomaly; it is characteristic of how professional sports teams allocate capital. Revenue accrues through media rights, arena economics, and premium seating; costs follow through payroll, coaching, and facilities. The spread is thin and volatile. Private buyers — and the institutional sponsors now permitted to hold minority stakes — underwrite sports investments on a fundamentally different basis: scarcity value, long-duration capital appreciation, and optionality across adjacent businesses (real estate, media, betting, sponsorship). Public equity markets, priced on quarterly earnings and compared against the full investable universe, cannot replicate that underwriting logic. The result is a persistent discount.
For FSG, the calculus is particularly nuanced. Liverpool FC is the most globally recognizable asset in the FSG portfolio, with brand equity that arguably exceeds any franchise in North American sports. An IPO that captured Liverpool’s valuation would theoretically be transformative for FSG’s balance sheet. But the Manchester United precedent is directly applicable: United has been publicly traded since 1991, initially in London and later on the NYSE, and has spent most of that period trading at a steep discount to what private buyers have consistently assessed as its intrinsic value. Ratcliffe’s 66% premium to the public market price was not generosity — it was simply the cost of acquiring an asset that public equity markets had been systematically undervaluing for years. FSG’s leadership has reviewed that history. The conclusion they have reached — that Liverpool’s value is better realized through selective minority transactions (as with the 2021 RedBird Capital Partners $750 million investment at a ~$4.7 billion club valuation) than through a public listing — reflects exactly the lesson the MSGS experience reinforces.
The Bull Case for Going Public: The counter-argument exists, and it is not trivial. Public markets offer a cost of capital that private transactions cannot match, a liquidity event for founder-class shareholders who have been holding illiquid sports equity for decades, and a mechanism for attracting international retail investors who cannot access private sports funds. The Atlanta Braves Holdings spin-off from Liberty Media — which ultimately narrowed the discount and provided a cleaner platform for private buyer interest — illustrates that a well-structured public vehicle can work, provided the asset is sufficiently isolated from a larger corporate complexity problem. The Braves’ market cap of approximately $3 billion is roughly in line with current private-market estimates for the franchise, a far better alignment than MSGS has historically achieved.
There is also a league-level dynamic to consider. The NBA’s new 11-year, $76 billion media rights deal — which took effect with the 2025–26 season — represents the most transformative revenue event in the league’s history, distributing meaningfully higher national media payments to every franchise. Teams that went public, or considered doing so, in the pre-deal era were working with a fundamentally different revenue profile than they would be today. A post-deal public listing for a franchise with a clean corporate structure and no Dolan-style governance complexity would enter markets with a more defensible earnings story than any sports IPO of the prior decade.
The Analyst Take: The MSGS experience is more likely to deter than to accelerate IPO activity among the major multi-club platforms. The fundamental problem — that public equity markets price sports assets on metrics that are structurally misaligned with how private buyers value the same assets — is not one that can be resolved by better investor relations or more transparent financial reporting. It is endemic to the asset class. What the MSGS episode does demonstrate, however, is that a thoughtfully structured spin-off into pure-play vehicles can narrow the discount materially — particularly when the spin-off catalyzes targeted minority investment from firms that understand the private-transaction comp set. That is a more viable template for large conglomerates like FSG or HBSE than a full IPO: selective monetization of individual assets through minority stake sales to institutional buyers, at private-market premiums, without subjecting the broader portfolio to the permanent discount that public listing tends to impose.
The Bottom Line
MSG Sports’ proposed spin-off is the most visible current example of the structural mismatch between public equity markets and private sports franchise valuations. The $13.5 billion combined private appraisal against a $9.6 billion enterprise value is a 29% discount that has persisted for years — driven by Dolan family governance complexity, cross-entity subsidization, and the inherent inability of public markets to price scarcity value the way private buyers can. The Ratcliffe/Manchester United template — a 66% premium to the public market price — is the clearest recent demonstration of what that gap looks like when a sophisticated private investor decides to close it.
The dominant trend in professional sports ownership has been toward multi-club consolidation — MLSE, FSG, HBSE, Kroenke, SEG — because shared infrastructure genuinely creates operational leverage. The lesson of MSG is not that this model fails, but that it fails when corporate complexity outweighs operating integration. The multi-club operators that have built durable value have done so through genuine shared services — unified commercial teams, single-arena platforms, and coordinated media rights strategies — not through financial engineering. The Rogers/Bell transaction for MLSE at C$12.5 billion is what a functional multi-club model produces. The Dolan corporate web is what dysfunction produces.
For institutional investors, the spin-off creates the clearest entry point into Knicks and Rangers equity in the history of either franchise. Silver Lake’s existing 10% stake in MSGS positions it advantageously for any post-spin minority transaction. For new entrants, the structural template is established: observe the public-private gap, price the entry at a premium to the public market and a discount to private-transaction precedent, and negotiate governance rights in exchange. The question is not whether institutional capital will flow to both post-spin entities. It is which firms move first and at what premium.
For more updates like this, subscribe to stay informed on private capital activity across global sports assets.
Join the FanClub Community
FanClub is a GP co-invest private client platform and registered investment advisor (RIA) that provides out-of-the-box tools to connect the top General Partners (GPs) & Investment Managers in pro sports with a network of the world’s most prestigious private investors seeking sports as the next frontier in alternative asset investing
FanClub Quick Links
TLDR? Follow our Instagram & Twitter Pages at @fanclubsports & @fanclubsportshq
Don’t have time for a morning newsletter? No worries, FanClub has you covered. FanClub condenses the Owner’s Club Newsletter into a series of short Instagram & Twitter posts so you can catch all the highlights, even if you miss the game.
Instagram | Twitter | TikTok | Apple Podcasts | Spotify
Deals
FanClub has active GP-led deals across major pro sports leagues, European football, moto racing, women’s sports, emerging leagues and GP stakes
Email or book a call with our CEO David Mirynech to find out what is active on the platform (dave@fanclubsports.co)
Investment Advisory Services, investment opportunities, and marketplace are offered through FanClub Sports Management LLC, a registered investment adviser.
The information contained herein is provided for informational and discussion purposes only and is not intended to be a recommendation for any investment, service, product, or other advice of any kind, and shall not constitute or imply an offer of any kind. Any investment opportunities and/or products or services shown here will only be completed pursuant to formal offering materials, a letter of intent, and/or any other agreements as determined by FanClub containing full details regarding risks, minimum investment, fees, and expenses of such transaction. The terms of any product, service, or particular investment opportunity, including size, costs, and other characteristics, are set forth in the applicable constituent documents for such product, service or particular investment opportunity and may differ materially from those presented in this presentation. Such terms are subject to change without notice.
Quotes included in these materials related to FanClub’s services should not be construed in any way as an endorsement of FanClub’s advice, analysis, or other service rendered to its clients.

Stay tuned for the latest FanClub deals and sports updates!